Walk into almost any Indian bank branch this month, and you'll meet a familiar ritual. Young or old executive, phone in one hand, register in the other, intercepts you near the queue. "Sir, please deposit your money in an FD, very good rate is there." Ask what happens to your money, how it compares with a mutual fund, or why this account and not another, and the pitch usually stalls. The number is confident. The reasoning is not. That gap, for sure, is not a training failure. It is a business model issue.
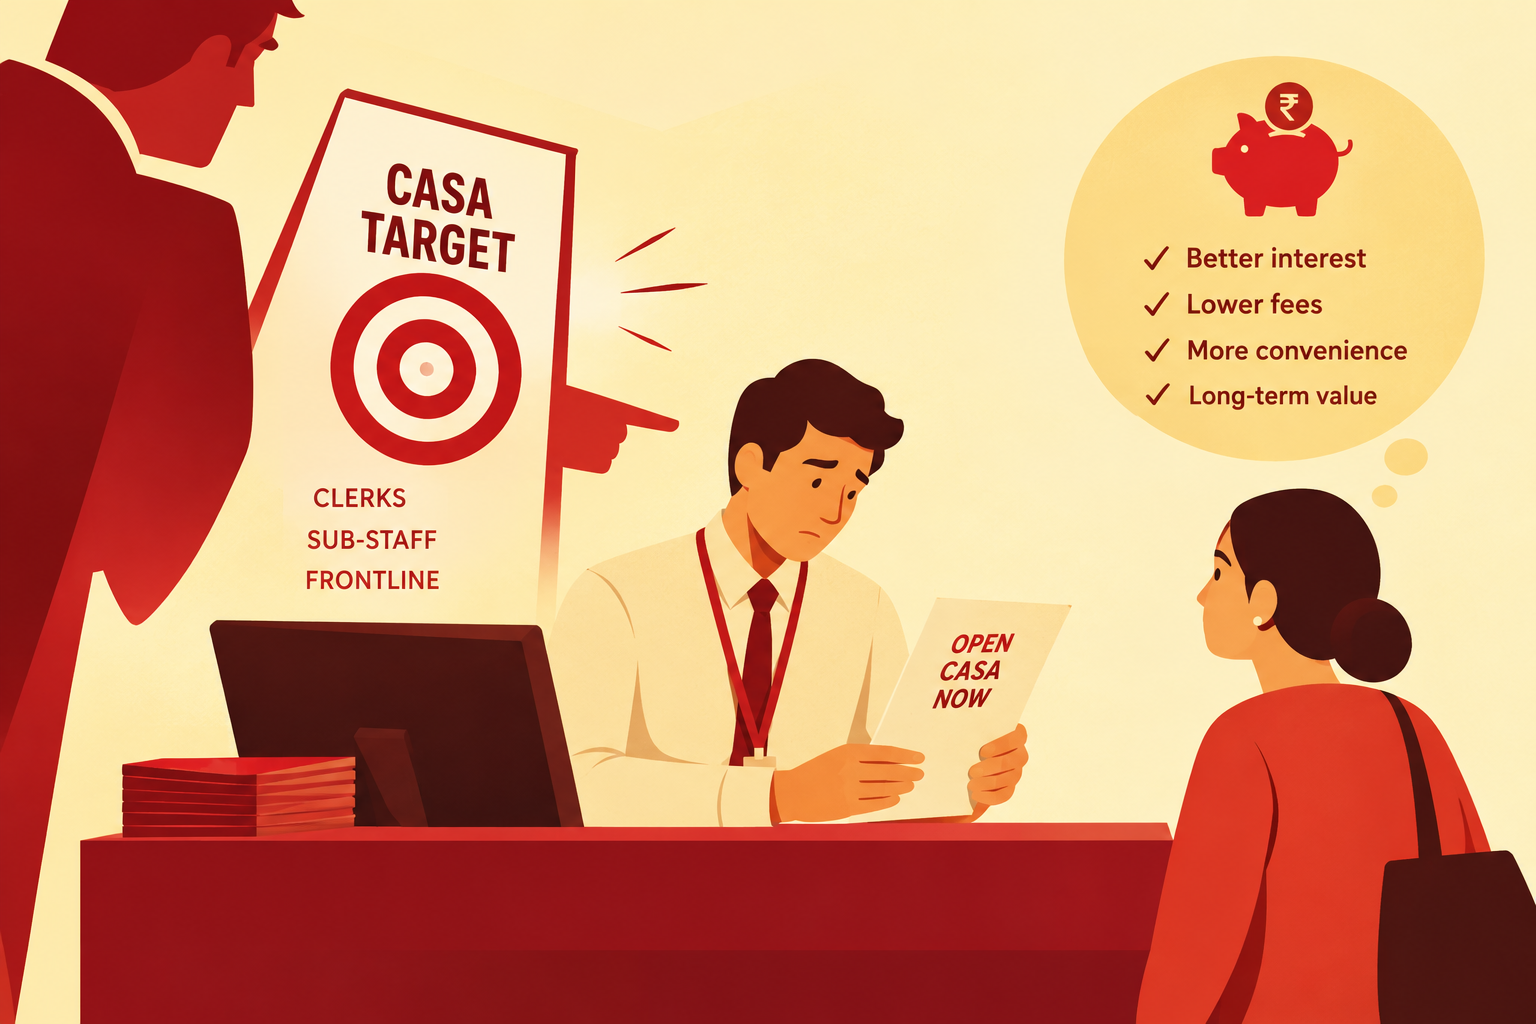
Start with why this is happening at all. Loans have been growing faster than deposits for months, and the cheap, sticky money that current and savings accounts once supplied is shrinking as a share of the total. Households have discovered mutual funds and direct equity, and every rupee that leaves a savings account for a systematic investment plan is a rupee a bank must now replace with something costlier. Somewhere in a head office, a CASA target lands on a regional office. The regional office breaks it into branch targets. The branch manager breaks it further, and hands out numbers to whoever is standing in the branch that week, whether or not selling was ever their job.
This last part is not exaggeration at all. At one of the top 5 banks in India, an employees' coordination committee complained to management after regional offices circulated spreadsheets asking clerks and subordinate staff, roles with no sales mandate in their service conditions, to commit to specific deposit amounts they would personally canvass. Public sector banks have long run "cash for CASA" schemes, paying branch staff a flat sum for every account opened, with certificates and small bonuses for whoever brings in the most. Even the Department of Financial Services has leaned in, convening account-opening camps for government employees explicitly framed around shoring up CASA balances. None of this is secret. It is official strategy, executed by people who did not design it and often cannot explain it.
That's the employee side. The customer side is worse, and it has a track record.
For years, the same branch network has been the delivery mechanism for India's biggest consumer-finance scandal that nobody quite calls a scandal: bancassurance mis-selling. Surveys have found that roughly six in ten customers of large private banks, and more than half of public-sector bank customers, report having been mis-sold a product. The pattern is consistent enough to be a genre: a customer walks in wanting to move money or renew a deposit, and walks out having signed for a multi-year insurance policy, often not understanding it was insurance at all. Regulators have finally moved on this. The Reserve Bank's new conduct rules, due to bite from mid-2027, will ban bundling insurance with loans and require separate, explicit consent for every product, with refunds where banks get it wrong. That a rule like this was needed at all tells you how far selling had drifted from any customer's actual need.
Here is the throughline.
Indian banks, when a number must move, have one lever: push it through the front line, without giving the front line a real story to tell.
It worked, in a narrow sense, for insurance, because commissions were rich enough to make the push profitable even as trust quietly eroded. Now the same lever is being pulled for deposits, because the CASA number must move and a target is the only pressure a head office knows how to apply. The tool has not changed. Only the product being pushed through it has.
This matters because a target and a reason are not substitutes for each other, and banking has quietly forgotten the difference. A target tells an employee what number to hit by Friday. A reason tells a customer what problem is being solved for them. When the second is missing, the first still gets delivered, awkwardly, apologetically, "sir please deposit," because the employee has been given a number without being given an argument. Customers can tell. They comply once, resent it, and move their real money to the app that never asks them to do anyone a favour.
None of this requires a grand reinvention, only an honest one.
A frontline employee needs a genuine reason to hand a customer, not a script but an actual answer: this account gives you same-day access your mutual fund doesn't, this salary account waives a fee that was quietly costing you money, this FD ladder matches when your child's fees are due.
That is a five-minute conversation a bank could teach, if it decided the conversation mattered as much as the number. Incentive structures need to stop rewarding accounts opened and start rewarding accounts that are still active, and satisfied, a year later.
The deposit problem is real, and banks are right to worry about it. But a customer who doesn't know why they're depositing money is a customer who will find out, eventually, that they didn't need to. Indian banking has already run this experiment once, with insurance, and the regulator had to step in to clean it up. Running it again with deposits, only louder and with more urgency, is not a strategy. It is muscle memory from a mistake the industry hasn't finished paying for.