As banks race to automate with AI, a regulator argues that having some friction is good.
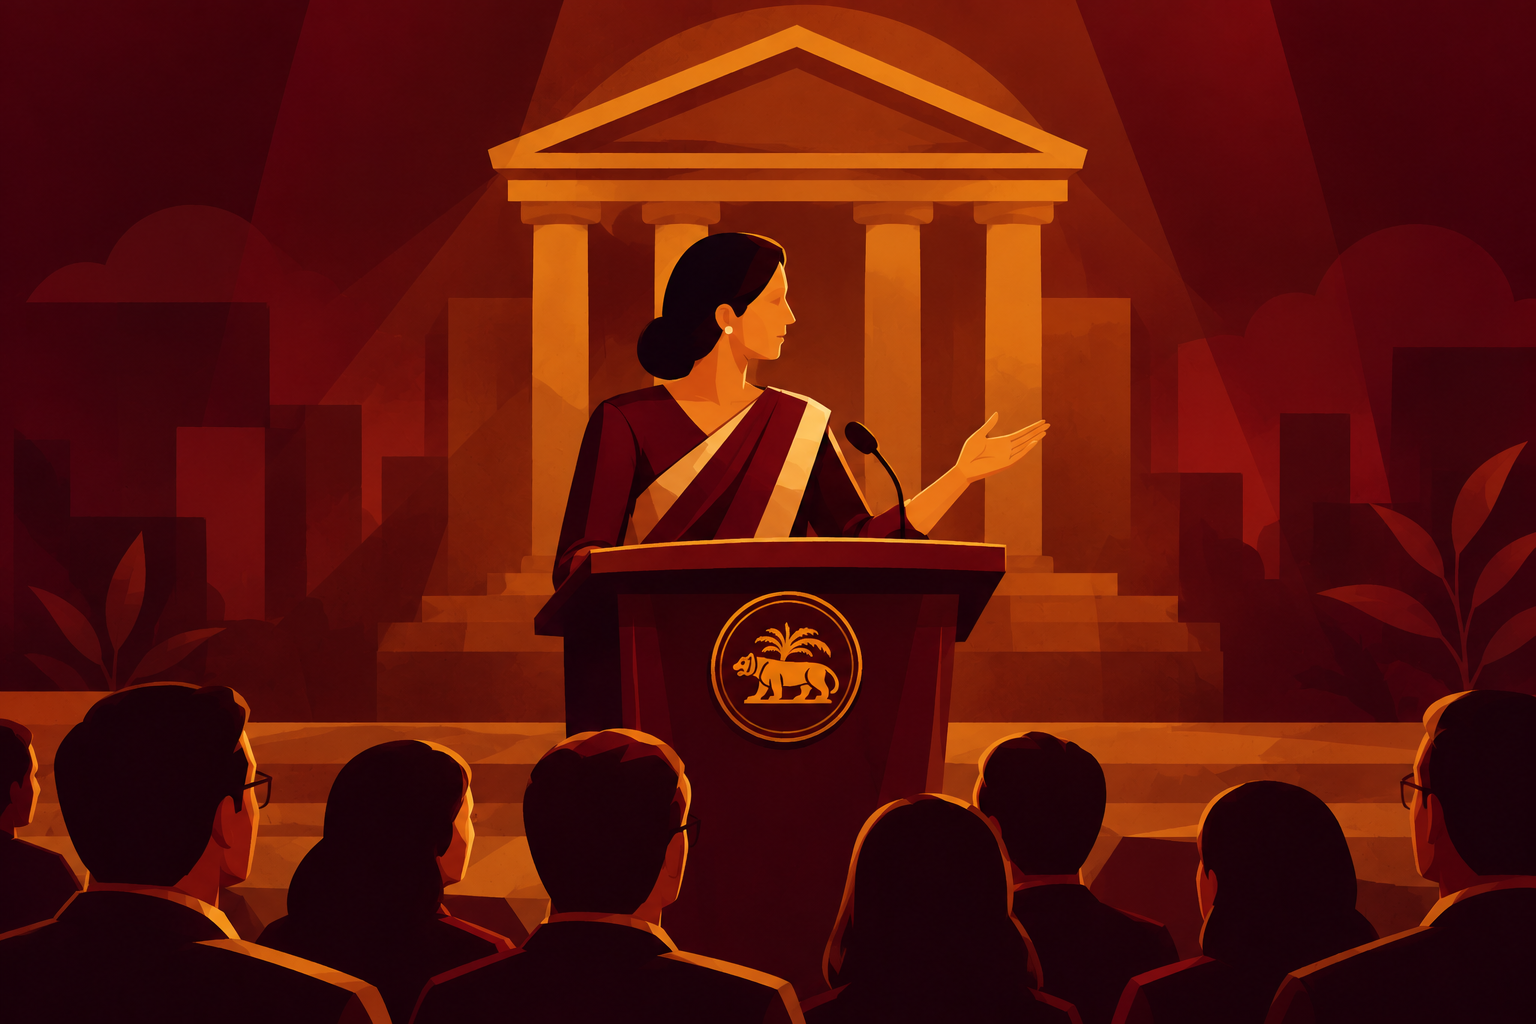
In the rhythm of Indian banking, the weeks around Diwali were once called the “busy season,” when credit demand increases with weddings, home purchases and business expansions. This year, with the festive season gathering pace, RBI Dy. Governor used the occasion to say something unfashionable in a moment of financial-technology exuberance: Slow down, or at least know what you are slowing down.
The speech, delivered at a Financial Express banking summit whose theme was “The Next Balance Sheet: Growth. Trust. Resilience.”, was framed as three propositions. Taken together, they amount to a supervisory manifesto for a financial system that is getting bigger, faster and harder to see into.
The case for friction
The first proposition is the most pointed. Panels at the summit were devoted to frictionless onboarding, AI-driven underwriting and autonomous workflows, all things the industry sells as unalloyed progress. The regulator’s reply was that “not every friction in finance is inefficiency.” A second pair of eyes on a transaction, an independent verification or a cooling-off period costs time but buys protection against error, fraud and adverse selection.
The practical test that was offered is easy to remember: when a step is removed in the name of speed, what risk was it controlling, and where does that control live now? If no one can answer this question then, “process simplification may in fact be control dilution.”
Now, this is not the traditional risk aversion Indian household thinking. It has some strong rationale. American regulators have spent the past two years learning the same lesson. The collapse of Synapse, a fintech middleware firm, in 2024 left customers at partner banks unable to reach their money. It was a technology failure, true, but at the same time, no one could say with certainty who held what, and which party was responsible for reconciling it. The Dy. Governor's warning that a process “may be outsourced, but the responsibility associated with the institution’s licence remains with the regulated entity” is the Indian version of the same point. It is also a pre-emptive rebuke to any bank that assumes a fintech partner can absorb the liability.
Trust, off the balance sheet
The second proposition is more philosophical, and in some ways more interesting. Trust, as we all know, appears nowhere on a balance sheet. It is not booked when built and shows up only when impaired, through customer attrition, litigation, penalties and reputational damage. Because it is invisible, it is easy to underfund when growth is strong.
This makes it very difficult to understand when trust is most often tested. The first is product sales, where better data and sharper targeting can “sharpen the consequences of poor incentive design.” Anyone who followed the Wells Fargo accounts scandal will recognize the pattern: volumes rise, and trust quietly drains. The second is the use of customer data, where the question is both of consent and the intended use. The third is grievance handling: complaints should be treated as risk intelligence rather than tickets to be closed.
The most analytically interesting passage to me concerns the system as a whole. A customer defrauded through a chain of accounts will not distinguish between the bank where the scam began, the one the money passed through and the one that hosted a mule account. To the victim, “the financial system has failed.” Weak controls at one institution therefore impose a trust cost on all of them. In simple words, there's a collective accountability on fraud and a message to the weaker links that their lapses can become everyone’s problem.
Resilience measured in hours
The third proposition updates a familiar concept. Capital, liquidity and provisions still matter, but in a digital system resilience “must also be measured in time”: how fast an institution can detect a problem, understand it, decide and restore critical services. The evidence presented was the 2023 U.S. bank run, in which $42 billion left Silicon Valley Bank in a single day, a pace that no line outside a branch could have produced.
The sharpest line may be the least dramatic. A useful gauge of governance is how long it takes bad news to travel through an institution. Problems are rarely wholly invisible beforehand. An auditor flagged an exception, a compliance officer raised a concern, a business unit saw an odd pattern. The failure is usually that the information did not reach someone with authority to act, or did not arrive in time. Boards, in this telling, should go looking for bad news rather than wait for it.
What is missing
For all its clarity, the speech is a statement of philosophy, not policy. In my humble opinion, the regulator has been bullish on philosophical governance in the last few years but bearish on actually spurring innovation or clear direction. It's apparent in the targeted technology here, which is Artificial Intelligence. It's almost been four years since ChatGPT and AI reaching every corner of the world. Yet, we're yet to have a clear direction on adoption of it while the banks clearly are in wait for it to come from RBI before making any significant investments. Continuing with the same theme, in this speech as well, it announces no new rule, deadline or penalty. It does not say how a bank should measure the “time to escalate,” or how supervisors will judge whether controls have kept pace with growth. Nor does it grapple with the commercial tension at the heart of the matter: lenders competing for customers in a market where a rival’s instant approval is a competitive weapon will not volunteer to add friction.
The ending is the most culturally specific, and perhaps the most effective. The Diwali custom of opening new account books with the words “Shubh Labh” was mentioned, pointing out that the blessing asks not only for gain (labh) but for propriety (shubh). It is a tidy way of saying that how a profit is made matters as much as its size.
The read-through
Central bankers rarely give speeches by accident, and the timing here is also important. India’s lenders enter this cycle with clean books and comfortable capital, which is exactly when supervisors tend to worry most. Good times are when controls slip or ignored and incentives drift. The message to the industry is less a scolding of any nature than an early notice about the questions examiners are likely to ask: Where did the control go? Who owns the third party’s mistakes? How fast would you know?